Fluorspar Price Trend Q2 2026: China vs India Pricing Breakdown
Fluorspar just posted a fresh set of numbers for May 2026, and the gap between markets is bigger than what we saw with a lot of other industrial minerals lately. China’s pricing USD 482.51 per metric ton, FOB. India’s landed cost comes in at USD 549.85 per metric ton, CIF. That’s not a small spread — it’s over USD 67 per ton, and anyone buying in bulk feels that difference on the invoice.
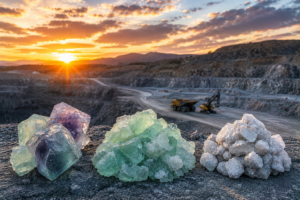
Fluorspar doesn’t get talked about much outside chemical and metallurgical circles. But it’s the mineral behind hydrofluoric acid production, steel fluxing, and a chunk of the refrigerant supply chain. Aluminum smelting relies on it too. When fluorspar prices shift, the effects show up downstream in places most people never connect back to a mineral mined in China or Mexico.
Fluorspar Prices: China vs India Right Now
Numbers first.
| Product | Region | Incoterm Basis | Price | Last Updated |
|---|---|---|---|---|
| Fluorspar | China | FOB | USD 482.51/MT | May 2026 |
| Fluorspar | India | CIF | USD 549.85/MT | May 2026 |
USD 67.34 apart. That’s a real gap, and part of it comes down to something simple: China’s number is FOB — it stops at the export port, before freight and insurance get added. India’s is CIF — freight and insurance already baked in. So the two figures aren’t measuring quite the same thing.
Quick breakdown of what’s driving that comparison:
- FOB pricing reflects the cost at origin, before the buyer takes on shipping.
- CIF pricing includes freight and insurance to the destination — India’s buyers are paying for that convenience.
- Both prices are single-month snapshots from May 2026, not a running average.
China dominates global fluorspar output by a wide margin, so its FOB rate functions almost like a reference price for the rest of Asia. India, without much domestic fluorspar supply of its own, ends up as a price-taker — and that shows in the higher CIF number.
What’s Behind the Fluorspar Price Trend
Mining output. China controls most of the world’s fluorspar production. Any policy change on mining quotas, environmental enforcement, or export licensing there moves global supply almost instantly. There isn’t a deep bench of alternative suppliers to fall back on.
Downstream chemical demand. Hydrofluoric acid production eats up a large share of fluorspar output, and HF demand tracks refrigerant manufacturing closely. Steel production pulls fluorspar too, for use as a flux in smelting.
Freight costs matter a lot here — probably more than with most minerals. Fluorspar ships in bulk, and rate swings on the China-India shipping lane hit the landed cost directly. A jump in bunker fuel prices can widen that CIF-FOB gap within weeks.
Currency plays its part as well. Dollar-denominated pricing means a weaker rupee raises India’s real cost even if the quoted price never moves.
A Few Questions Buyers Keep Asking
Is China’s lower fluorspar price always the better deal? Not necessarily. FOB pricing skips freight, insurance, and the logistics of actually getting material into your facility. Once you add those in, the real cost gap between sourcing from China versus paying India’s CIF rate often shrinks — sometimes it disappears entirely.
Why doesn’t India just produce more fluorspar domestically? Geology, mostly. India doesn’t have large accessible fluorspar reserves comparable to China’s. Building out domestic capacity would take years and serious capital — not something that solves near-term supply gaps.
Does the price gap ever flip? It’s happened before, briefly, during periods of Chinese export restrictions. Rare, but not impossible. Worth keeping an eye on if you’re locking in long-term contracts.
What This Means for Buyers and Investors
Chemical manufacturers sourcing hydrofluoric acid inputs should treat this spread as more than background noise. A 12-13% price gap between origin and landed cost adds up fast across annual procurement volumes.
Steel producers using fluorspar as a flux face a similar calculation. Locking in supply contracts without checking current pricing risks locking in a bad deal — fluorspar markets move on mining policy news faster than most buyers expect.
Investors watching critical minerals exposure might find the India side more interesting. Limited domestic supply plus rising demand from chemicals and steel creates a structural reason for import dependency to persist — and potentially for prices to stay elevated relative to China’s export rate.
Looking Ahead: Q2 2026 Outlook
Where’s this heading through the rest of Q2? China’s export policy remains the biggest wildcard. Any tightening on mining quotas or environmental restrictions could push FOB prices up fast, and India’s CIF rate would follow within weeks.
Demand-side, refrigerant manufacturing tends to pick up seasonally, which could add pressure from the consumption end too. Nothing here points toward prices easing off in the near term — if anything, the setup favors continued firmness.
Buyers negotiating contracts right now shouldn’t assume May’s numbers hold steady. Pull updated pricing before signing anything long-term.
Conclusion
The fluorspar price trend for Q2 2026 shows China at USD 482.51/MT FOB against India’s USD 549.85/MT CIF — a gap shaped by mining concentration, freight costs, and India’s reliance on imports. For chemical manufacturers, steel producers, and anyone tracking critical minerals, this isn’t a spread to ignore. Fluorspar moves on supply-side news more than most people realize, and staying current on pricing is part of managing that risk properly.
FAQ Section
What is the fluorspar price trend in China and India right now?
China’s fluorspar is priced at USD 482.51/MT FOB, India’s at USD 549.85/MT CIF, both as of May 2026. The gap reflects incoterm differences plus India’s dependence on imports since it lacks significant domestic reserves.
Why is fluorspar more expensive in India?
India’s CIF price includes freight and insurance costs China’s FOB figure doesn’t carry. Add limited domestic mining and reliance on imported supply, and the landed cost climbs. Shipping lane conditions can widen or narrow that gap further.
What drives fluorspar prices globally?
China’s mining output dominates supply, so policy shifts there move prices fast. Demand from hydrofluoric acid production and steel fluxing matters too. Freight costs and currency movements add on top, especially for import-dependent markets like India.
How volatile are fluorspar prices?
More volatile than many industrial minerals, mainly because supply concentrates so heavily in China. Export quota changes or environmental crackdowns can shift FOB prices within weeks. Buyers relying on older pricing data risk missing real cost movements.
What’s the fluorspar price outlook for Q2 2026?
Chinese export policy is the main variable to watch. Any supply tightening there would likely push both FOB and CIF prices higher. Seasonal refrigerant demand adds further upward pressure, so prices easing off soon looks unlikely.